
Report from Fact.MR, an initiative of Eminent Research and Advisory Services; authored by Principal Consultant S.N. Jha (edited by Naved Ahmed):
- The digital printing for flexible packaging market is valued at USD 10.2 billion in 2026.
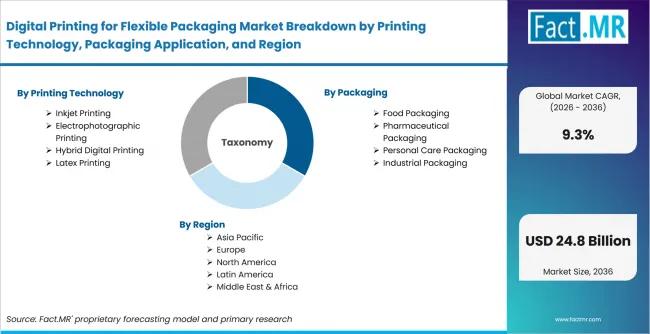
- Demand is projected to increase to USD 24.8 billion by 2036.
- The market is forecast to record 9.3% CAGR from 2026 to 2036 as converters add digital capacity for shorter runs, versioned artwork, and faster packaging replenishment.
What are the defining numbers behind Digital Printing for Flexible Packaging Market growth?
USD 14.6 billion in absolute opportunity is anticipated between 2026 and 2036. Inkjet Printing and Food Packaging form the main technology and application share anchors, while Food & Beverage, Packaging Converters, and Plastic Films define the largest end-use, customer, and substrate positions.
- What demand drivers define the market?
- Brand owners need more packaging versions across flavors, pack sizes, promotions, languages, and regional assortments, which makes plate-free job changes commercially useful when volumes are fragmented.
- Packaging converters need production routes that shorten the interval between approved artwork and finished rollstock while keeping color, registration, web handling, and finishing under control.
- Food, pharmaceutical, and personal-care buyers need traceable artwork and documented print systems because a packaging change can affect product information, migration review, sealing, barrier performance, and regulatory approval.
- Recyclability programs are pushing converters to retest inks, coatings, primers, laminations, and mono-material film structures, creating recurring qualification work around digitally printed flexible substrates.
- Which key segments were analyzed?
- By Printing Technology: Inkjet Printing is expected to hold 44% share in 2026 as water-based and UV inkjet platforms address rapid job changeovers and direct digital imaging.
- By Packaging Application: Food Packaging is projected to account for 43% share in 2026 because snack and frozen-food brands generate frequent artwork, promotional, and replenishment requirements.
- By End-use Industry: Food & Beverage is anticipated to capture 46% share in 2026 as packaged foods and beverages create a wide mix of flexible-packaging formats and SKU variations.
- By Customer Category: Packaging Converters are forecast to represent 41% share in 2026 because they make the equipment, workflow, substrate, lamination, and finishing decisions that determine digital production economics.
- By Substrate Material: Plastic Films are estimated to account for 39% share in 2026 owing to established use of polyethylene and polypropylene films across pouches, rollstock, and other flexible pack structures.
- What is the analyst opinion at Fact.MR?
- Shambhu Nath Jha, Principal Consultant at Fact.MR, states: “Flexible packaging buyers are not selecting a press only by print speed. They are choosing a production model that can absorb artwork changes, SKU fragmentation, short replenishment cycles, substrate transitions, and tighter food-contact documentation without creating excess inventory. Fact.MR opines that inkjet and hybrid systems will win where converters can connect color control, web handling, lamination, finishing, and job data into one repeatable workflow.”
- What are the strategic implications?
- Converters should compare digital presses by usable finished-pack throughput rather than engine speed alone, including priming, curing or drying, lamination, slitting, pouch making, quality inspection, and changeover time.
- Food-packaging teams should qualify ink, primer, film, adhesive, and barrier combinations as a complete structure before expanding a digitally printed design across multiple product families.
- Brand owners should use digital capacity selectively for launches, regional versions, promotional runs, and demand-uncertain SKUs while retaining analog economics for stable long-run work where it remains advantageous.
- Press suppliers should strengthen workflow automation, color management, remote service, and substrate application support because operational consistency determines whether digital capacity becomes repeatable production rather than a sampling tool.
- Film and laminate suppliers should give converters clear surface-treatment, adhesion, sealing, and recyclability guidance so new substrates do not create avoidable press and converting downtime.
How does the Digital Printing for Flexible Packaging Market break down by segment?
Inkjet Printing leads Printing Technology at 44%, Food Packaging leads Packaging Application at 43%, Food & Beverage leads End-use Industry at 46%, Packaging Converters lead Customer Category at 41%, and Plastic Films lead Substrate Material at 39% in 2026.
Why does Inkjet Printing lead Printing Technology?
Inkjet Printing holds 44% share in 2026.
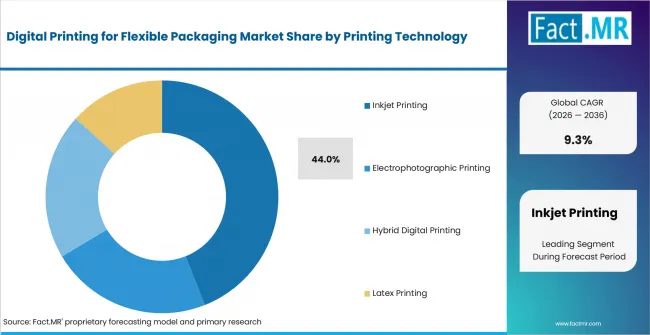
Inkjet Printing is projected to hold 44% share in 2026 because the imaging step can change from job to job without plates or cylinders, giving converters a practical route for versioned graphics, variable information, and shorter production lots. UV Inkjet serves applications that value rapid cure and strong surface interaction, while Water-based Inkjet is important where converters and brand owners prefer water-based ink systems for selected flexible-packaging structures. Electrophotographic Printing remains relevant through Dry Toner Printing and Liquid Toner Printing, especially where mature digital color workflows and short-run economics are already embedded. Hybrid Digital Printing combines Digital-Flexographic Hybrid or Digital-Gravure Hybrid architectures when variable imaging must sit beside analog coating, white, varnish, or converting steps. Latex Printing, through Water-based Latex and UV Latex configurations, provides another route where substrate compatibility and application requirements justify it. Fujifilm launched the water-based Jet Press FP790 for flexible packaging in March 2024, and SCREEN announced full-scale flexible-packaging production with the water-based Truepress PAC 830F at Chiyoda in July 2026. These investments show why inkjet is increasingly evaluated as a production platform rather than only a proofing or label technology.
Why does Food Packaging lead Packaging Application?
Food Packaging accounts for 43% share in 2026.
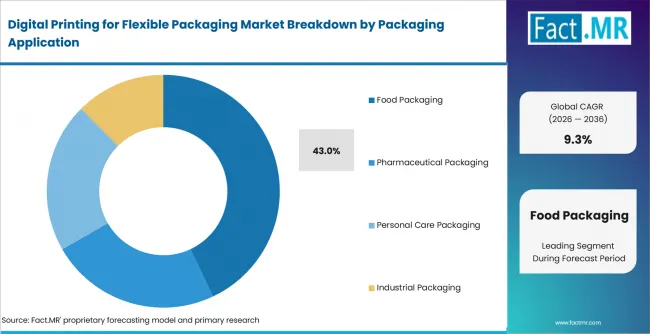
Food Packaging is forecast to account for 43% share in 2026 because Snack Packaging and Frozen Food Packaging combine frequent SKU changes with strict demands for legibility, seal integrity, barrier performance, and consistent graphics across repeated replenishment cycles. Pharmaceutical Packaging follows through Blister Packaging and Medical Device Packaging, where version control and approved copy increase the cost of artwork errors. Personal Care Packaging includes Cosmetic Pouches and Refill Packaging, which use visual differentiation and smaller launches to support brand portfolios. Industrial Packaging covers Chemical Packaging and Agricultural Packaging, where durable identification and controlled product information can matter more than decorative complexity. Flexible food packaging also imposes migration and ink-system discipline. Fujifilm states that its Jet Press FP790 was created to address the regulatory requirements of the food-packaging business, while Xeikon has positioned its CX500 dry-toner platform for flexible pouches using food-safe toner. That combination of run-length flexibility and packaging compliance keeps food applications commercially central.
Why does Food & Beverage lead End-use Industry?
Food & Beverage represents 46% share in 2026.
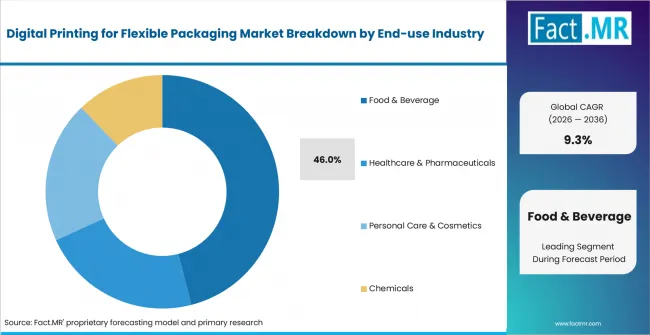
Food & Beverage is anticipated to represent 46% share in 2026 because Processed Foods and Beverages move through large retail, food-service, and online channels that require repeated packaging replenishment and frequent portfolio changes. Digital print is especially useful when demand is split across flavors, seasonal graphics, regional languages, promotional editions, or market tests that do not justify conventional setup across every version. Healthcare & Pharmaceuticals follow through Pharmaceutical Products and Medical Devices, where artwork control and lot-related information can increase the value of digital workflows even when volumes are lower. Personal Care & Cosmetics spans Skincare Products and Hair Care Products, where packaging appearance and launch cadence create high design intensity. Chemicals, including Specialty Chemicals and Agrochemicals, add industrial applications where product identification and version management matter. Food and beverage therefore lead not because every job is short, but because the sector produces a wide mix of high-volume core SKUs and lower-volume variants that converters must schedule on the same production network.
Why do Packaging Converters lead Customer Category?
Packaging Converters account for 41% share in 2026.
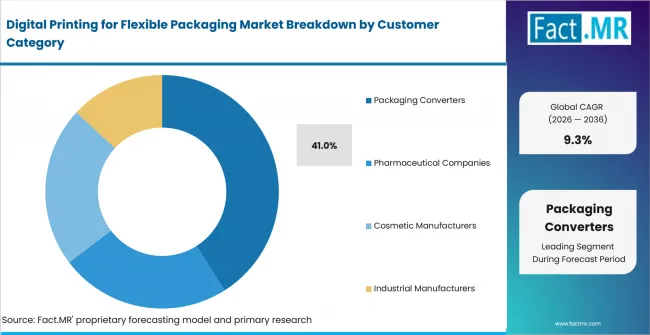
Packaging Converters are estimated to account for 41% share in 2026 because Flexible Packaging Manufacturers make the operating decisions that turn a digital image into sellable rollstock or pouches, while Brand Owners influence specifications, color standards, approved artwork, and service expectations. Pharmaceutical Companies follow alongside Contract Packaging Companies and Medical Device Manufacturers, where controlled copy and product change procedures affect print orders. Cosmetic Manufacturers, Personal Care Brands, and Household Product Companies create smaller design-rich runs and refill formats that can favor fast changeovers. Industrial Manufacturers, Chemical Suppliers, and Agricultural Product Companies require durable identification and controlled job data across more utilitarian pack structures. HP describes the Indigo 200K as a digital press designed for flexible-packaging converters, while ePac has built its manufacturing model around digitally printed short- and medium-run flexible packaging. The leading customer share therefore reflects the converter’s role as both capital buyer and production integrator.
Why do Plastic Films lead Substrate Material?
Plastic Films hold 39% share in 2026.
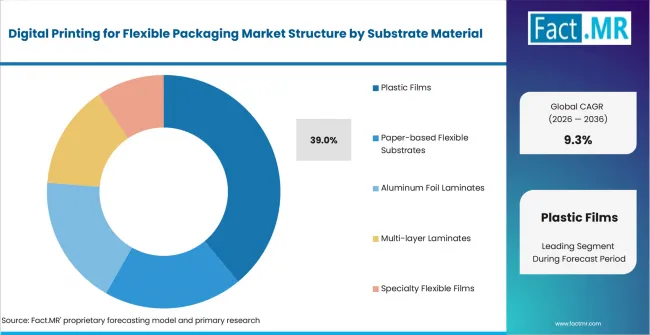
Plastic Films are forecast to hold 39% share in 2026 because Polyethylene (PE) Films and Polypropylene (PP) Films are widely used as sealant, print, and structural layers across flexible packs. Paper-based Flexible Substrates, including Coated Paper, gain relevance where stiffness, fiber content, and brand presentation fit the product. Aluminum Foil Laminates remain important when light, oxygen, or moisture barrier requirements justify a foil layer. Multi-layer Laminates include High-barrier Films and Recyclable Mono-material Films, forcing converters to balance protection, sealability, machinability, and end-of-life design. Specialty Flexible Films include Synthetic Fiber Substrates and Biodegradable Flexible Films for narrower applications. The substrate decision is becoming more technical because print adhesion, primer selection, curing or drying, barrier coatings, lamination, and recycling design interact. Germany’s 2025 minimum standard for recycling-friendly packaging gives companies a structured way to assess recyclability, while the EU Packaging and Packaging Waste Regulation starts applying broadly from August 2026. Digital-print suppliers that qualify new film structures quickly can reduce the commercial risk of substrate transitions.
What is accelerating Digital Printing for Flexible Packaging Market adoption, and what is holding it back?
SKU fragmentation, on-demand conversion, regulatory artwork changes, and substrate redesign support digital adoption. Long-run analog economics, food-contact qualification, downstream converting constraints, film variability, and workflow integration restrain faster replacement of established flexographic and gravure production.
What does the drivers impact analysis show?
| DRIVER | IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Short-run SKU proliferation and artwork versioning | Qualitative | North America, Europe, and Asia Pacific | Medium term (2-4 years) |
| Converter migration to plate-free on-demand workflows | Qualitative | Global converting hubs | Medium term (2-4 years) |
| Recyclability redesign and mono-material qualification | Qualitative | Europe with global brand spillover | Short term (<= 2 years) |
| E-commerce and direct-to-consumer replenishment cycles | Qualitative | USA, China, South Korea | Short term (<= 2 years) |
| Water-based, low-migration, and application-specific ink qualification | Qualitative | Food and pharmaceutical packaging markets | Long term (>= 4 years) |
- SKU fragmentation: Brand portfolios increasingly split production across flavors, pack sizes, promotional graphics, regional languages, private-label versions, and trial launches. Digital production becomes more attractive when artwork changes are frequent enough that analog setup, inventory, and obsolescence outweigh lower long-run unit cost.
- On-demand workflow: Removing plates or cylinders from the imaging step can compress job preparation, but the commercial benefit appears only when prepress, color approval, web handling, lamination, slitting, and pouch conversion are scheduled around the same fast-turn objective.
- Recyclability redesign: New mono-material and recyclable structures require converters to retest print adhesion, barrier layers, heat resistance, sealing, and appearance. The resulting qualification cycles give digital presses a role in development lots and staged commercialization before a brand commits to larger volumes.
- E-commerce replenishment: U.S. retail e-commerce sales increased 9.8% year over year in the first quarter of 2026, while China reported continued expansion in online retail during the first five months of 2026. Faster digital sales channels can produce more volatile SKU-level replenishment, which raises the value of responsive packaging capacity.
- Ink qualification: Water-based and other application-specific ink systems are expanding the addressable job set, but each film, primer, coating, adhesive, and end-use combination still needs technical validation. Suppliers that provide repeatable application data can shorten a converter’s qualification cycle.
What does the opportunity impact analysis show?
| OPPORTUNITY | IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Wide-web inkjet production for flexible packaging | Qualitative | USA, Japan, Europe, and Asia Pacific | Medium term (2-4 years) |
| Hybrid digital-flexographic and digital-gravure production cells | Qualitative | Europe, North America, and Asia Pacific | Medium term (2-4 years) |
| Recyclable mono-material film printing programs | Qualitative | Europe and global brand supply chains | Medium term (2-4 years) |
| Localized digital converting networks for short lead times | Qualitative | USA, Europe, and Asia Pacific | Short term (<= 2 years) |
| Automated color, workflow, inspection, and job-data integration | Qualitative | Global converters | Long term (>= 4 years) |
- Wide-web inkjet: Flexible packaging has historically depended on analog web printing for production scale. New dedicated inkjet platforms from Fujifilm and SCREEN broaden the range of jobs that can be evaluated digitally, particularly when converters need wider webs, water-based ink options, and production-grade web handling.
- Hybrid production: Digital-Flexographic Hybrid and Digital-Gravure Hybrid systems can keep analog strengths where coating, white, varnish, or special effects remain efficient while inserting digital imaging for variable graphics and versioning. The opportunity is operational, not simply technical, because a hybrid cell must remove rather than add changeover complexity.
- Mono-material programs: Recyclable Mono-material Films create an opening for suppliers that can prove ink adhesion, heat resistance, lamination compatibility, and print quality on redesigned PE- or PP-rich structures. A press vendor that qualifies materials with film, adhesive, and converter partners can make substrate change easier for brand owners.
- Localized networks: ePac’s digitally focused production model illustrates how converters can use geographically distributed capacity to support short and medium runs, rapid artwork changes, and regional brand needs. Similar network models can reduce the amount of finished printed packaging that must be produced far ahead of demand.
- Workflow automation: Automated preflight, color management, variable-data handling, inspection, production analytics, and finishing integration can lift press utilization without changing the print engine itself. This creates room for software and service differentiation among competing suppliers.
What does the restraints impact analysis show?
| RESTRAINT | IMPACT ON CAGR | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Long-run unit economics versus flexographic and gravure printing | Qualitative | Global high-volume converters | Long term (>= 4 years) |
| Food-contact, migration, and regulated-application qualification | Qualitative | Europe, USA, Japan, and pharmaceutical markets | Short term (<= 2 years) |
| Lamination, slitting, and pouch-making bottlenecks after printing | Qualitative | Global converters | Medium term (2-4 years) |
| Substrate variability, treatment, and ink-adhesion risk | Qualitative | Global film-printing operations | Medium term (2-4 years) |
| Capital cost, operator skills, and workflow integration | Qualitative | Small and mid-sized converters | Short term (<= 2 years) |
- Long-run economics: Flexographic and gravure printing remain efficient for stable, repeat, high-volume jobs where setup cost is spread across long runs. Digital investment therefore depends on the customer’s job mix, not on an assumption that every flexible-packaging order should migrate to digital.
- Qualification burden: Food, pharmaceutical, and medical-device applications can require migration review, approved ink or toner systems, controlled artwork, and documentation around the complete packaging structure. A technically printable film is not automatically commercially qualified for every end use.
- Finishing bottlenecks: Faster digital imaging can simply move the constraint downstream if lamination, curing, slitting, inspection, pouch making, or quality release remain batch oriented. Converters need balanced capacity across the whole process to capture short-turn economics.
- Film variability: Surface energy, thickness, stretch, heat sensitivity, coatings, and pre-treatment differ among flexible substrates. Poor adhesion or web stability can create waste that offsets the setup savings associated with digital imaging.
- Integration cost: A production press also requires digital front-end software, color standards, variable-data control, maintenance skills, service coverage, and operator training. Smaller converters may adopt more slowly when the business case depends on simultaneous workflow and finishing upgrades.
Which countries are scaling the Digital Printing for Flexible Packaging Market fastest?
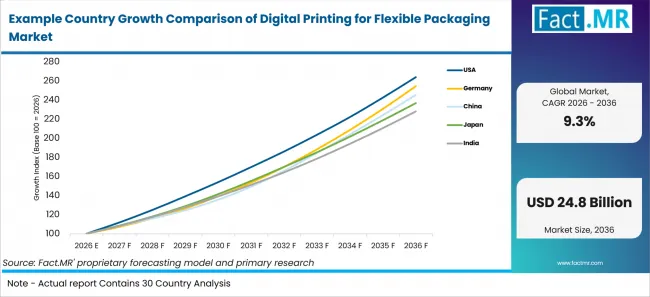
Among the covered countries, USA leads at 10.2% CAGR through 2036. Germany follows at 9.8%, China at 9.4%, Japan at 9.0%, India at 8.6%, France at 8.2%, and South Korea at 7.8%.
- USA records the highest country CAGR at 10.2% as digital commerce, regional brand production, and an established converter base create a broad mix of short- and medium-run packaging work.
- Germany and China record 9.8% and 9.4% CAGR, respectively, but the commercial triggers differ: Germany emphasizes recyclability and technical packaging compliance, while China combines large-scale consumer goods production with expanding online retail.
- Japan records 9.0% CAGR as domestic press makers and converters develop water-based inkjet and digitally managed packaging workflows alongside a large e-commerce market.
- India, France, and South Korea record 8.6%, 8.2%, and 7.8% CAGR, supported respectively by food-processing expansion, plastic-packaging transition, and digitally intensive retail channels.
Regional analysis covers North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa.
| COUNTRY | CAGR THROUGH 2036 |
|---|---|
| USA | 10.2% |
| Germany | 9.8% |
| Japan | 9.0% |
| India | 8.6% |
| France | 8.2% |
| South Korea | 7.8% |
What is driving USA growth through 2036?
10.2% CAGR through 2036, supported by a large converter network, rapid digital-commerce replenishment, and continuing investment in digitally printed flexible packaging.
USA buyers combine national consumer brands with a deep base of regional food, beverage, nutrition, pet, personal-care, and specialty-product companies that frequently manage many SKUs. The U.S. Census Bureau reported that first-quarter 2026 retail e-commerce sales increased 9.8% from the first quarter of 2025. That channel does not automatically create a digital-print order, but it exposes brand owners to faster SKU-level demand changes and makes overproduction of printed packaging more costly. HP and ePac also announced further expansion of ePac’s HP Indigo fleet in February 2026, reinforcing the country’s installed digital flexible-packaging capability. The market is forecast to record 10.2% CAGR through 2036 as converters use digital capacity for launches, regional versions, replenishment, and demand-uncertain products alongside established analog lines.
Who leads the Digital Printing for Flexible Packaging Market?
HP Inc. is the disclosed share leader at 12.7%. FUJIFILM Holdings Corporation and SCREEN Holdings Co., Ltd. provide dedicated flexible-packaging inkjet platforms, while Xeikon N.V., Durst Group AG, Bobst Group SA, Domino Printing Sciences plc, Canon Inc., and Konica Minolta, Inc. extend the competitive field through toner, inkjet, hybrid, label-and-packaging, workflow, and converting systems. ePac Holdings, LLC participates from the converter side with a production model built around digital flexible packaging.
HP Inc. holds the disclosed 12.7% share and anchors its flexible-packaging offer around HP Indigo technology, including the Indigo 200K press. The commercial role extends beyond the engine because converters need digital front-end workflow, color control, service, consumables, and web-production support. HP’s February 2026 announcement with ePac described further expansion of ePac’s Indigo fleet, giving the supplier a visible production reference across a digital-first flexible-packaging network. The remaining providers compete through documented product roles, substrate compatibility, workflow integration, and service coverage rather than a single share ranking.
FUJIFILM Holdings Corporation targets direct flexible-packaging production with the Jet Press FP790, a water-based inkjet press developed for flexible-packaging applications and food-packaging requirements. SCREEN Holdings Co., Ltd. addresses the same production problem with the water-based Truepress PAC 830F and announced full-scale flexible-packaging production with Chiyoda in July 2026. Xeikon N.V. provides a different architecture through dry-toner systems such as the CX500, which has been deployed for flexible pouch production with food-safe toner. These platforms compete through usable web width, ink or toner chemistry, substrate qualification, productivity, and downstream converting fit rather than one common print-engine specification.
Durst Group AG broadens digital and hybrid competition through its Tau platform and the Tau G3 portfolio for labels and flexible packaging, with hybrid configurations that combine digital inkjet and conventional processes. Bobst Group SA integrates digital print, analog modules, workflow, and inline converting across its All-in-One platform and added FLEXJET to expand digital multilayer production. Domino Printing Sciences plc contributes high-resolution inkjet and hybrid integration through the N730i architecture, linking digital printing with substrate preparation and inline finishing. These suppliers are relevant where converters want one production cell to handle more of the job instead of moving rolls among separate processes.
Canon Inc. participates through the LabelStream LS2000 and a broader labels-and-packaging strategy built on water-based industrial inkjet. Konica Minolta, Inc. contributes high-speed digital label systems such as the AccurioLabel 400 and workflow automation that are relevant to converters operating adjacent label and flexible-packaging businesses, although the equipment mix and addressable flexible substrates differ from dedicated wide-web flexible-packaging platforms. ePac Holdings, LLC differs from the other profiled companies because it is primarily a converter rather than a press manufacturer; its distributed digital production model demonstrates how short- and medium-run flexible packaging can be commercialized around rapid artwork-to-order workflows. Competition through 2036 is expected to revolve around finished-pack throughput, food-contact suitability, substrate breadth, color consistency, service response, workflow automation, and the ability to integrate lamination and finishing.
Which companies are the key providers?
Key companies include HP Inc.; Konica Minolta, Inc.; Xeikon N.V.; Canon Inc.; Durst Group AG; FUJIFILM Holdings Corporation; Bobst Group SA; Domino Printing Sciences plc; ePac Holdings, LLC; and SCREEN Holdings Co., Ltd.
- HP Inc.
- Konica Minolta, Inc.
- Xeikon N.V.
- Canon Inc.
- Durst Group AG
- FUJIFILM Holdings Corporation
- Bobst Group SA
- Domino Printing Sciences plc
- ePac Holdings, LLC
- SCREEN Holdings Co., Ltd.
What does this report address?
- The report provides strategic intelligence on Digital Printing for Flexible Packaging across Printing Technology, Packaging Application, End-use Industry, Customer Category, Substrate Material, and Region.
- Segment analysis quantifies only the leading subsegment for each parent: Inkjet Printing, Food Packaging, Food & Beverage, Packaging Converters, and Plastic Films.
- Country outlook compares USA, Germany, China, Japan, India, France, and South Korea using the country CAGR set through 2036 without converting those growth rates into country market sizes or shares.
- Competitive analysis profiles HP Inc. and the other named providers. HP Inc. carries the disclosed 12.7% company share, while the remaining providers are discussed by documented market roles rather than ranked.
- The analysis evaluates short-run production, versioning, web handling, ink and toner chemistry, substrate transitions, lamination and finishing, workflow automation, and the commercial boundary between digital and conventional printing.
- Application coverage connects food, pharmaceutical, personal-care, and industrial packaging requirements to the specific converter and substrate decisions that determine digital-print adoption.
What does the Digital Printing for Flexible Packaging Market cover?
The market covers digital printing technologies and associated production solutions used to image flexible packaging substrates for commercial packaging. It includes inkjet, electrophotographic, hybrid digital, and latex routes across plastic films, paper-based flexible substrates, foil laminates, multi-layer laminates, and specialty flexible films. Revenue is tied to digital printing and conversion activity where flexible packaging is the principal application, not to the value of the packaged product itself.
The commercial boundary follows the job from digital prepress and press selection through substrate qualification, print production, and the converter interfaces that determine finished-pack output. Food, pharmaceutical, personal-care, and industrial applications are included because they impose different requirements for graphics, barrier structure, migration control, version management, and production lot size. Conventional flexographic and gravure processes are considered only where they are integrated into the Hybrid Digital Printing segment or provide necessary competitive context.
What is included in the market?
Included Printing Technology categories are Inkjet Printing, Electrophotographic Printing, Hybrid Digital Printing, and Latex Printing together with its defined subsegments for UV and water-based inkjet, dry and liquid toner, digital-flexographic and digital-gravure hybrid systems, and water-based and UV latex. Included applications and end uses follow the market segmentation, including food, pharmaceutical, personal-care, and industrial flexible packaging.
The analysis includes Packaging Converters and the other customer categories in the segmentation, together with Plastic Films, Paper-based Flexible Substrates, Aluminum Foil Laminates, Multi-layer Laminates, and Specialty Flexible Films. It also considers digital workflow, color management, substrate treatment, ink or toner qualification, lamination, slitting, pouch conversion, and related production decisions when those factors directly affect purchase, utilization, or recurring demand for digital flexible-packaging printing.
What is excluded from the market?
The scope excludes conventional flexographic or gravure printing jobs that do not contain a digital printing step, rigid packaging production, and label-only applications when they are not part of flexible-packaging output. It also excludes the value of packaged food, pharmaceuticals, cosmetics, chemicals, and other finished goods, because the market measures digital flexible-packaging printing rather than downstream product sales.
Country CAGR is used only to compare growth rates across countries and is not converted into country market size or share. Segment and company-share discussion remains confined to the quantified leaders in the market structure. Driver, opportunity, and restraint tables use qualitative impact labels where no numerical impact is established.
How was the Digital Printing for Flexible Packaging Market research conducted?
Fact.MR used a hybrid research approach that connects demand-side packaging activity with converter adoption, digital press capability, substrate requirements, and provider participation. Market sizing combines forecast values with segment structure and country growth patterns, while external primary sources support factual context around regulation, retail activity, food processing, e-commerce, and company technology.
- What did primary research cover?
- Primary research is structured around flexible-packaging converters, digital-press users, prepress and color teams, film and laminate suppliers, brand packaging managers, procurement teams, food and pharmaceutical packaging specialists, service technicians, and production managers. Discussions focus on job length, digital-versus-analog routing, waste, changeover time, substrate qualification, lamination and finishing capacity, color consistency, service response, and the conditions under which a digital job becomes repeat production.
- What did desk research cover?
- Desk research reviews official statistics, packaging regulation, recycling requirements, government food-processing and e-commerce data, company filings, official product documentation, technology announcements, and converter investment disclosures. Competing market-research publishers are not used as evidence. Company sources are used only for direct facts about their own presses, workflows, installations, investments, and application positioning.
- How was market sizing and forecasting performed?
- Market sizing and forecasting connect flexible-packaging print demand with the share of work that can be routed through digital production. The model considers SKU fragmentation, average job length, artwork changes, digital press adoption, food and pharmaceutical packaging activity, customer mix, film and laminate usage, substrate redesign, and the ability of converters to convert printed web into finished packaging. Forecast logic also accounts for the fact that long, stable runs may remain on flexographic or gravure equipment while digital capacity concentrates on high-mix and shorter-turn work.
- How were the data validated and updated?
- Validation combines cross-checks of forecast values, segment shares, country growth rates, market boundaries, and competitive roles. Country explanations are compared with local official indicators, while company statements are limited to verifiable products, installations, and market roles. Updates incorporate regulatory changes, digital-press launches, converter installations, substrate developments, and shifts in end-use production that can change digital job economics during the forecast period.
What is the report’s scope and coverage?
| ATTRIBUTE | DETAILS |
|---|---|
| Quantitative Units | USD Billion |
| Market Definition | Digital printing technologies, production systems, and digitally focused conversion solutions used to print flexible packaging substrates for commercial packaging applications |
| Printing Technology | Inkjet Printing; Electrophotographic Printing; Hybrid Digital Printing; Latex Printing |
| Packaging Application | Food Packaging; Pharmaceutical Packaging; Personal Care Packaging; Industrial Packaging |
| End-use Industry | Food & Beverage; Healthcare & Pharmaceuticals; Personal Care & Cosmetics; Chemicals |
| Customer Category | Packaging Converters; Pharmaceutical Companies; Cosmetic Manufacturers; Industrial Manufacturers |
| Substrate Material | Plastic Films; Paper-based Flexible Substrates; Aluminum Foil Laminates; Multi-layer Laminates; Specialty Flexible Films |
| Regions Covered | North America; Europe; Asia Pacific; Central & South America; Middle East & Africa |
| Countries Covered | USA; Germany; China; Japan; India; France; South Korea |
| Key Companies Profiled | HP Inc.; Konica Minolta, Inc.; Xeikon N.V.; Canon Inc.; Durst Group AG; FUJIFILM Holdings Corporation; Bobst Group SA; Domino Printing Sciences plc; ePac Holdings, LLC; SCREEN Holdings Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Hybrid top-down and bottom-up analysis using flexible-packaging print demand; job length and SKU complexity; digital press adoption; substrate mix; food, pharmaceutical, personal-care, and industrial packaging requirements; converter participation; workflow automation; provider activity; and country growth |
How is the Digital Printing for Flexible Packaging Market segmented?
-
By Printing Technology:
- Inkjet Printing
- UV Inkjet
- Water-based Inkjet
- Electrophotographic Printing
- Dry Toner Printing
- Liquid Toner Printing
- Hybrid Digital Printing
- Digital-Flexographic Hybrid
- Digital-Gravure Hybrid
- Latex Printing
- Water-based Latex
- UV Latex
- Inkjet Printing
-
By Packaging Application:
- Food Packaging
- Snack Packaging
- Frozen Food Packaging
- Pharmaceutical Packaging
- Blister Packaging
- Medical Device Packaging
- Personal Care Packaging
- Cosmetic Pouches
- Refill Packaging
- Industrial Packaging
- Chemical Packaging
- Agricultural Packaging
- Food Packaging
-
By End-use Industry:
- Food & Beverage
- Processed Foods
- Beverages
- Healthcare & Pharmaceuticals
- Pharmaceutical Products
- Medical Devices
- Personal Care & Cosmetics
- Skincare Products
- Hair Care Products
- Chemicals
- Specialty Chemicals
- Agrochemicals
- Food & Beverage
-
By Customer Category:
- Packaging Converters
- Flexible Packaging Manufacturers
- Brand Owners
- Pharmaceutical Companies
- Contract Packaging Companies
- Medical Device Manufacturers
- Cosmetic Manufacturers
- Personal Care Brands
- Household Product Companies
- Industrial Manufacturers
- Chemical Suppliers
- Agricultural Product Companies
- Packaging Converters
-
By Substrate Material:
- Plastic Films
- Polyethylene (PE) Films
- Polypropylene (PP) Films
- Paper-based Flexible Substrates
- Coated Paper
- Aluminum Foil Laminates
- Multi-layer Laminates
- High-barrier Films
- Recyclable Mono-material Films
- Specialty Flexible Films
- Synthetic Fiber Substrates
- Biodegradable Flexible Films
- Plastic Films
-
By Region:
- North America
- USA
- Europe
- Germany
- France
- Asia Pacific
- China
- Japan
- India
- South Korea
- Central & South America
- Middle East & Africa
- North America