PRODUCTION PRINTING
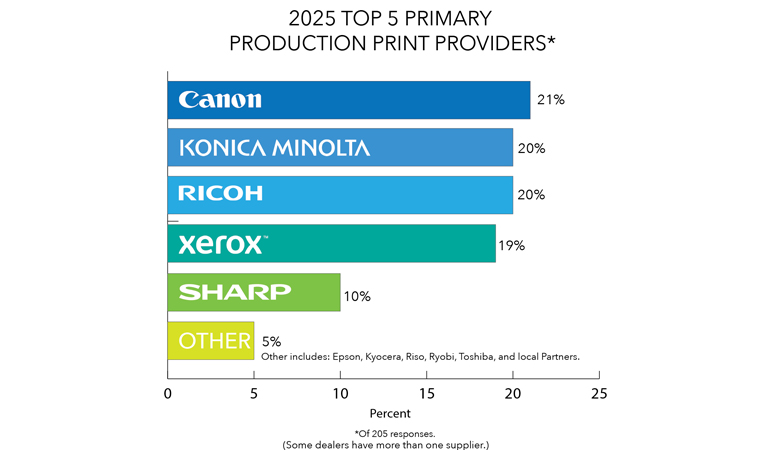
Production printing participation increased, with 172 dealers engaging in production printing—approximately 59% of those reported revenue from the category, up from 56% last year.
Participation varies sharply by dealer size. All 29 respondents with revenue above $40 million reported production printing revenue, as did 82% of those with revenue between $15 million and $40 million. Among dealers below $15 million, participation was 47%, little changed from 46% last year.
Despite broader participation, production printing accounted for an average of 4.8% of revenue across all dealers, down from 5.9%. Among dealers reporting production printing revenue, the average was 8.2%. These results suggest that the category remains a relatively small part of many dealerships’ businesses.
Primary production printing providers
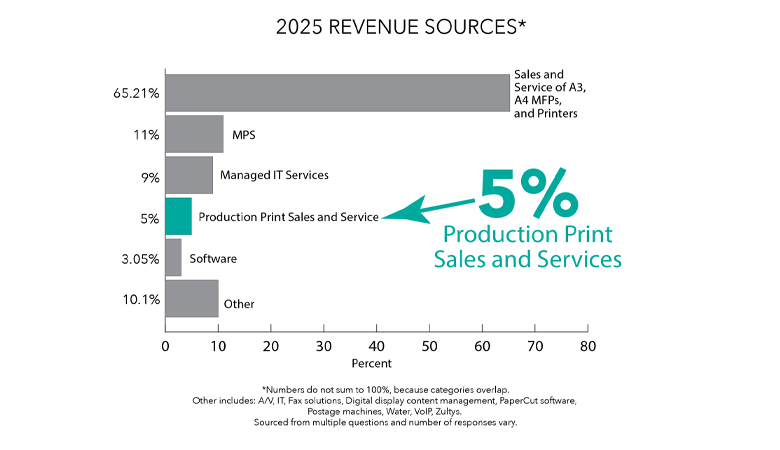
Of the respondents who engage in production printing, 172 dealers named a supplier. Canon led with 21%, followed closely by Ricoh and Konica Minolta, each at 20%, and Xerox at 19%. Sharp accounted for 10%. Canon’s lead over Ricoh amounted to just three respondents. (See graph at top.)
Last year, Ricoh led at 24%, followed by Xerox at 22%, Konica Minolta at 18%, Canon at 16%, and Sharp at 11%. The response count fell from 237 to 187, and dealers identifying Canon as their primary A3 supplier represented a larger share of the sample. These changes in participation should be considered when comparing supplier results, which refl ect respondents’ selections rather than overall market share.