INTRODUCTION
For 41 years, The Cannata Report’s Annual Dealer Survey has given independent office technology dealers a place to tell us, in their own numbers and words, how business is going. This year, we revised our questions to better understand how dealers are responding to declining A3 multifunction printer (MFP) revenue and where they are finding success beyond copiers.
Print sales and service, including managed print services (MPS), still account for about 76% of the average dealer’s revenue. Yet 52% of dealers now sell managed IT services, 59% sell production printing devices, and half plan to buy another company.
The differences by size are striking. Every dealer with more than $40 million in revenue offers production printing, nearly all offer managed IT, and most plan acquisitions. Among dealers with less than $15 million in revenue, fewer than half offer production printing, sell managed IT, or plan acquisitions. While 61% of dealers reported revenue growth, the gap between those that have diversified and those that have not is widening.
MPS, production printing, and managed IT services are helping replace lost A3 revenue. However, we question whether some dealers reporting production printing sales are equipped to compete in that business, given their total revenue. We believe some are classifying 60-page-per-minute (ppm) color and monochrome copiers as true production devices, which may distort the reported revenue figures.
Over the last three years, office technology dealers have repeatedly told us that weak profitability limits their ability to diversify and hire the people needed to improve their businesses. Dealers have shared their challenges, and the survey reveals they have found some solutions. Despite the gains from MPS, production printing, and managed IT, they don’t make up for the revenue lost in A3.
Survey Participants and Methodology
The Cannata Report’s 41st Annual Dealer Survey examines independent office technology dealers’ performance and business priorities. Conducted online for the 13th consecutive year, the survey received 301 submissions. After screening for duplicate, corrupted, and incomplete entries, 299 usable responses remained, down from 415 in 2025—a 28% decline.
Respondents represent approximately 17% to 20% of the estimated 1,500 to 1,800 independent dealers operating in the United States. Some dealer groups backed by private equity are unable to participate, leaving the largest organizations underrepresented. The smaller response pool and changes in its composition should be considered when comparing results with previous years.
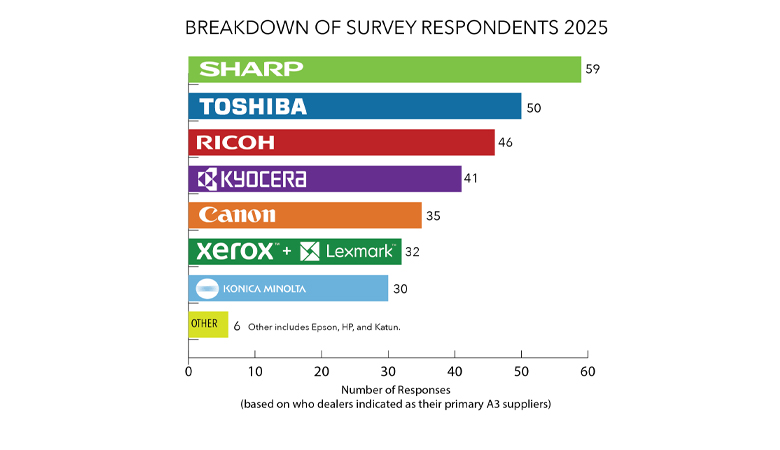
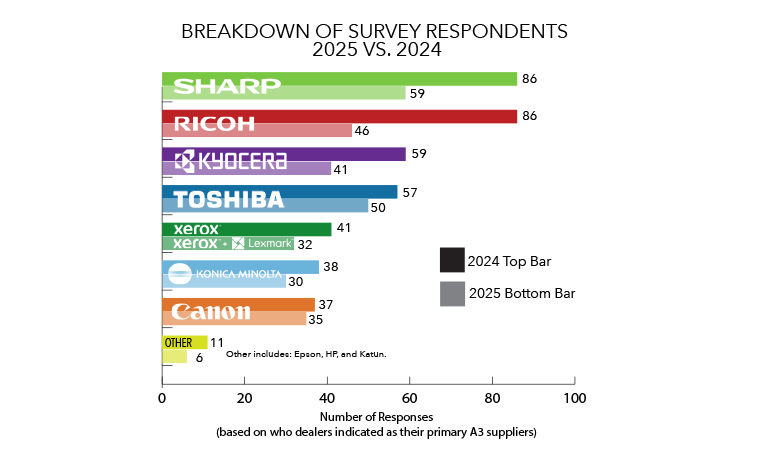
By primary A3 supplier, Sharp accounted for the largest group of respondents with 59 dealers, followed by Toshiba (50), Ricoh (46), Kyocera (41), Canon (35), Xerox (32), and Konica Minolta (30). These figures describe survey participation, not manufacturers’ market share. The remaining six dealers named Epson, HP, or Katun. Ricoh’s respondent count declined from 86 to 46, and Sharp’s from 86 to 59; Toshiba and Canon remained nearly unchanged.
Unless otherwise noted, results in this installment are based on all 299 respondents. Charts are based on the 293 dealers who identfied one of the seven major A3 manufacturers as their primary supplier.
Two changes affect year-over-year comparisons. Xerox now includes Lexmark following Xerox’s acquisition of the company. Revenue categories also changed: managed IT now includes cybersecurity, while a new “software solutions” category replaces the separate document management/ECM and VoIP/UCaaS categories. A3/A4 sales and service, managed print services (MPS), and production printing remain directly comparable with last year’s results. Managed IT services and software solutions do not.
Survey questions assess dealers’ positions relative to their 2025 performance. This year, unlike in previous years, results are being published exclusively in this combined October/ November issue. References to “last year’s survey” mean the 40th Annual Dealer Survey, published in The Cannata Report’s October and November 2025 issues.
Acknowledgements
The Cannata Report thanks ACDI, HP, Katun, Kyocera, Ricoh, Sharp, Stramaglio Consulting, Toshiba, U.S. Bank, and Xerox for encouraging dealer participation. Office technology survey respondents who are partners of any
of these 10 companies are eligible to receive two complimentary subscriptions to The Cannata Report. All others will be emailed PDFs of our Annual Dealer Survey issue.